August 2026 New Home Sales: Buyers Shift Toward Cheaper Homes as Affordability Worsens

New home sales rose in August but remained below last year’s pace. Buyers are increasingly concentrating at the bottom of the price distribution, and that shift is pulling the reported price of a new construction home lower.
Key Takeaways
- Sales are still soft. New home sales rose 6.4% in August but remained 2% below a year ago. The August gain came before mortgage rates moved above 7%.
- Buyers are shifting toward cheaper homes. Homes under $300,000 are the fastest-growing price range, with sales up 11% so far this year compared with 2025. That shift pulled both the median and average price of new construction homes lower in August.
- Fewer finished homes, not fewer buyers. Sales are down mostly because completions are down. The pool of new construction buyers is essentially unchanged from a year ago.
- Builders are behind the resilience. Builders have slowed the flow of new homes onto the market and are using incentives and cheaper homes to keep buyers engaged. Months’ supply stayed at 8.5, and inventory is slightly lower than a year ago.
New home sales rose in August. This points to a resilient sector, and most of that resilience comes from homebuilders adjusting to high mortgage rates. It is not evidence of a broader recovery.
Builders sold new homes at a seasonally adjusted annual rate of 684,000, up 6.4% from July but 2% below a year ago. Monthly new-home sales are volatile and carry wide margins of error, so one month rarely makes a trend.
There is another reason to be cautious about the August gain. It came before mortgage rates rose above 7%. August sales reflect buyers making decisions under better financing conditions than they face today.
The broader trend remains soft. Builders sold about 450,000 new homes from January through August, roughly 3% fewer than during the same period last year and the lowest January-through-August total since 2018. Sales remain about 4% above their 2016–2019 average for the same eight months.
The slowdown is mostly a supply story. Fewer new homes are being completed, while the number of buyers has held steady.

The weakness is concentrated in the West, where year-to-date sales are down 11%. Sales are roughly flat in the Northeast and only slightly lower in the Midwest and South. The South still accounts for more than six of every ten new homes sold.
Sales have shifted toward the cheapest homes
The more important story is what buyers are purchasing.
As mortgage rates climbed this summer and affordability worsened, sales moved down the price ladder. More than half of the new homes sold in August cost less than $400,000, up from 46% a year earlier. Homes priced at $1 million or more accounted for just 4% of sales, down from 7%.

The shift is concentrated at the very bottom. Homes under $300,000 are the fastest-growing price range this year, with sales up 11%.
| Price range | Jan.–Aug. 2025 | Jan.–Aug. 2026 | Change |
|---|---|---|---|
| Under $300k | 75k | 83k | +10.7% |
| $300k–$400k | 139k | 134k | −3.6% |
| $400k–$600k | 145k | 139k | −4.1% |
| $600k–$1M | 75k | 66k | −12.0% |
| $1M+ | 26k | 25k | −3.8% |
That shift matters for interpreting new-home prices.
In August, the average new-home price fell 8.8% from a year ago to $478,700, and the median fell 5.8% to $393,700. Those figures measure the homes that sold, not the change in price of the same home over time. A thinner slice of luxury sales in August did much of the work. Over the past three months, the declines are smaller: about 1% for the average price and about 3% for the median.
A simple mix exercise suggests the shift toward lower-priced homes can explain much of August’s decline in the reported average price. That does not mean comparable new homes have not fallen in price. It means the headline average and median are being pulled lower, in part, because buyers are purchasing a cheaper mix of homes.
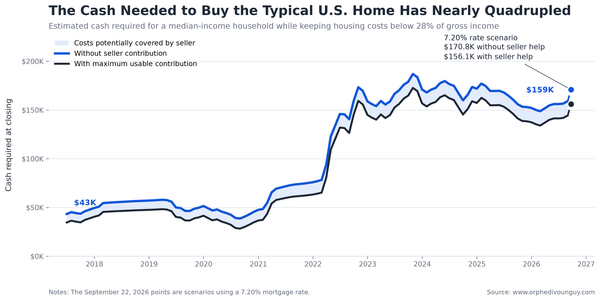
In other words, lower reported prices are also telling us something about affordability: buyers are moving toward the homes they can still afford.
Months’ supply is unchanged from a year ago
Inventory is slightly lower than a year ago, and builders—not buyers—are the reason.
There were 483,000 new homes for sale in August, about 2% fewer than a year earlier. The sales pace was also down about 2%, leaving months’ supply at 8.5, unchanged from August 2025.
Think of inventory as a tank. Homes flow in when builders list them for sale and flow out when buyers purchase them. The inflow has fallen because builders are bringing fewer new homes to market. The outflow—the number of buyers—is essentially unchanged from a year ago. With less coming in and about the same going out, inventory has edged down.

That is still elevated. Roughly five to six months of supply is commonly associated with a balanced market. Today’s 8.5 months gives buyers considerably more choice.
Not every home counted as inventory is ready for move-in. About three-quarters of the homes for sale, roughly 370,000, are still under construction or not yet started. The adjustment has come mostly from finished homes. Completed homes for sale fell 8% from a year ago, while homes not yet started rose 19%. Fewer finished homes means fewer homes ready to close, which is holding sales back. Even so, the stock of new homes for sale remains historically high. On a three-month average basis, inventory is roughly two-thirds above its 2016–2019 average.

New construction buyers are holding steady
Despite high mortgage rates, the pool of buyers searching for new construction has held up better than the sales numbers alone might suggest.

Our model-implied measure of new construction buyers is essentially unchanged from a year ago. The buyer pool is still about 12% smaller than in August 2019 and 45% below its October 2020 peak, but it has not fallen further over the past year.
Builders have tools that help keep those buyers in the market. They can offer mortgage-rate buydowns and other incentives, change floor plans and lot sizes, and build smaller or less expensive homes. They have also slowed the pace at which they bring new homes to market, which keeps inventory from piling up. Individual resale sellers can offer concessions too, but builders can deploy those tools more systematically and at scale. Those adjustments are the main reason the new-home market has held up: builders have changed what they build and how they sell it, and buyers have stayed.
The new home market still favors buyers. There are about 3% fewer new home listings per buyer than a year ago, but listings per buyer remain roughly three times higher than at the October 2020 low.
The verdict
The new-home market is softer than a year ago but resilient, and homebuilders deserve most of the credit.
Sales remain below last year’s pace, mostly because fewer homes are being completed rather than because buyers have left. Inventory is still elevated, and buyers are increasingly concentrating at the cheapest end of the market. The 6.4% August increase is encouraging, but it predates the latest move in mortgage rates above 7%. We will need the next few months of data to see how buyers and homebuilders respond to that additional hit to affordability.
For now, buyers have not disappeared. They have adjusted, and so have builders.
That adjustment is showing up in what sells, where it sells and at what price. Buyers have more choice and more room to negotiate than they did during the pandemic boom. For builders, the message is increasingly clear: the homes that are moving are the ones priced for today’s budgets.