October 2026 Housing Market Report: Pending Sales Fall To Lowest Level Since The Start Of the Pandemic
Key Takeaways
- Buying activity weakened again. Pending sales fell 3.6% from September, after a 4.9% drop the month before, and were down 15.1% from a year earlier, the steepest annual decline since May 2023.
- Homes for sale kept building as buyers pulled back. Active listings, the number of homes for sale at any point in the month, rose 0.9% from September to 1.53 million, the most since March 2020. The number of buyers fell 18% from a year earlier according to our estimates.
- Financing remains the hurdle. The 30-year mortgage rate averaged 7.33%. Monthly principal and interest on the median-priced home reached $2,137 with 20% down, the highest for any October in data going back to 2016, even as the median sale price slipped 0.4% from a year earlier.
October’s slowdown went beyond the usual seasonal pullback. After adjusting for seasonal patterns, 300,430 homes went under contract, the lowest level since April 2020. Closed sales fell to 274,987, their lowest level since December 2023.
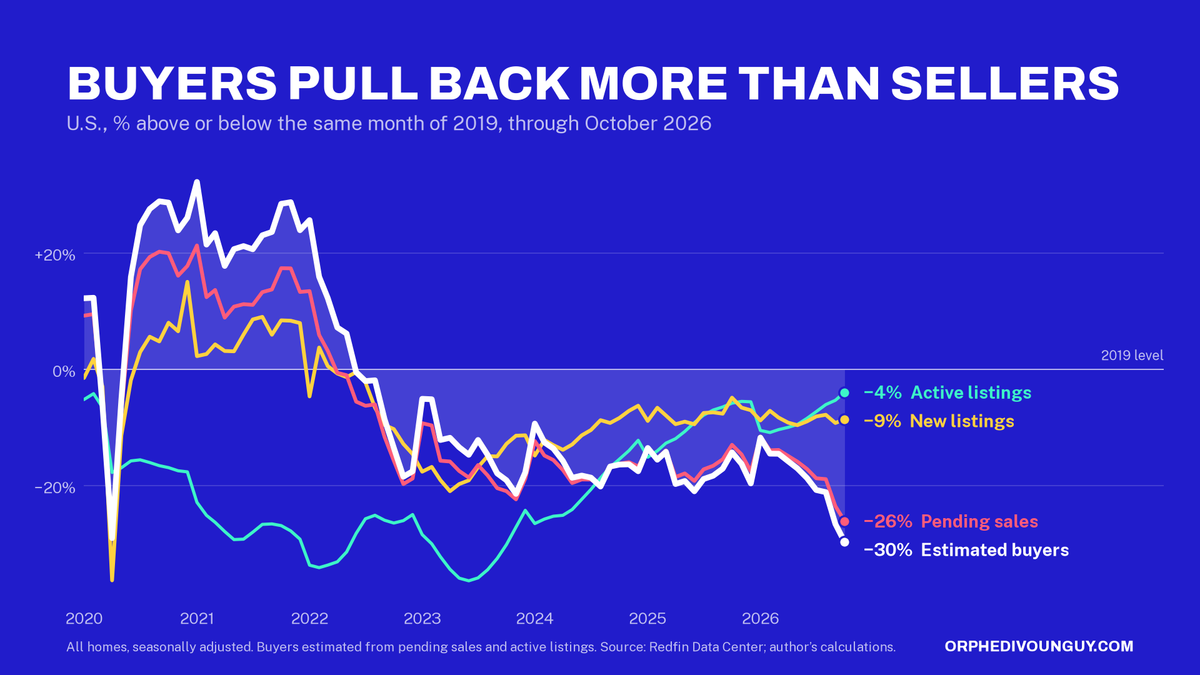
New listings fell 1.0% from September and 3.9% from a year earlier. Yet active listings rose 0.9% to 1.53 million homes, the most since March 2020. Fewer contract signings left more homes available for sale.
The estimated buyer pool fell 18.0% from a year earlier and 4.4% from September. Over the past two months it shrank 10%. The estimated number of buyers was 30% below October 2019. The number of buyers fell from a year earlier in every one of the 96 large metros with October data.
The median sale price was $388,634, down 0.4% from a year earlier, the first annual decline since May 2023. Borrowing costs moved the other way. The 30-year fixed mortgage rate averaged 7.33% in October, up from 6.25% a year earlier, lifting the monthly payment by $216. Higher rates added about $223; the slightly lower median price took off about $7.
Buyers have more homes to choose from and face less competition. But a wider selection does little for households that cannot afford the monthly payment, and that payment rose again in October.
National Market Details
Home Prices and Mortgage Payments
The median sale price fell 0.4% from a year earlier, the first annual decline since May 2023. This is a transaction-price measure; changes can also reflect the mix of homes sold.
With 20% down ($77,727), monthly principal and interest was $2,137, up 11.2% from a year earlier and the highest for any October in data going back to 2016. With 10% down ($38,863), it was $2,405. October’s average mortgage rate was the highest for any October since 2023. Payments exclude taxes, insurance, mortgage insurance and HOA charges.
Inventory and New Listings
Active listings, the number of homes for sale at any point during the month, totaled 1,526,984, up 2.0% from a year earlier and 0.9% from September. That was the highest level since March 2020, and the monthly increase was the largest since May 2025.
New listings totaled 372,431, down 3.9% from a year earlier, down 1.0% from September and 9% below October 2019. Active listings remained 4% below October 2019.
Sales
Closed sales fell 6.7% from a year earlier and 2.1% from September. Pending sales fell 15.1% annually and 3.6% monthly. Compared with October 2019, closed sales were down 21% and pending sales were down 26%.
Competition
Homes going under contract spent a median of 50 days on the market, one day longer than a year earlier and unchanged from September.
Active listings were equivalent to 5.1 months of October’s contract signings, up from 4.2 a year earlier and 4.9 in September. This ratio was the highest in data going back to January 2016. Redfin’s standard months of supply, based on closed sales, was 4.3 months.
Buyers
The 18.0% annual decline in estimated buyers was the steepest since May 2023. The 4.4% monthly decline followed a 5.8% drop in September. Listings available at any point during October rose about 24% relative to the estimated buyer pool from a year earlier. Seattle had the largest annual buyer decline among the 50 markets covered, at 36%, followed by San Diego at 31%.
Among the 97 large metros with enough October data, 32 had their lowest estimated buyer level relative to 2019 in data going back to 2016, including Phoenix, Dallas, Washington, D.C., Riverside, San Antonio and Charlotte.
Multifamily Homes with Two to Four Units
The median sale price was $449,350, up 6.9% from a year earlier and the highest for any October in data going back to 2016. Active listings reached 50,609, up 7.9% annually and 3% above October 2019, the most for any October since 2018.
Pending sales totaled 7,742, down 20.7% annually, and closed sales of 7,093 were the fewest for any October in data going back to 2016. Estimated buyers fell 25.2% annually and were 36% below October 2019. Monthly principal and interest was $2,471 with 20% down or $2,780 with 10% down, up 19.3% annually.
October Results for 50 Large Housing Markets
All homes. Redfin uses metropolitan divisions where available, so New York excludes Newark and Nassau County, and Los Angeles excludes Anaheim. Redfin’s October data have no sales or listing activity for Atlanta, no pending sales for Houston and no data for New Orleans, so those cells show n/a.
| Market | Median sale price | Price y/y | Active listings y/y | Active listings vs Oct 2019 | Pending sales y/y | Est buyers y/y | Est buyers vs Oct 2019 | Monthly P&I 20% down |
|---|---|---|---|---|---|---|---|---|
| United States | $388,634 | −0.4% | +2.0% | −4% | −15.1% | −18.0% | −30% | $2,137 |
| New York, NY | $793,211 | +4.4% | +1.7% | −33% | −14.4% | −17.1% | −18% | $4,363 |
| Los Angeles, CA | $921,012 | +1.9% | +1.5% | −4% | −17.4% | −20.6% | −43% | $5,065 |
| Chicago, IL | $378,669 | +3.3% | −2.0% | −41% | −7.6% | −8.6% | −19% | $2,083 |
| Dallas, TX | $398,599 | −1.1% | −6.4% | +23% | −18.2% | −20.2% | −31% | $2,192 |
| Houston, TX | $323,861 | −1.9% | +2.5% | +31% | n/a | n/a | n/a | $1,781 |
| Washington, DC | $577,968 | −1.2% | +8.8% | +6% | −19.4% | −23.9% | −46% | $3,179 |
| Philadelphia, PA | $303,931 | +4.1% | +12.9% | +3% | −11.0% | −15.0% | −37% | $1,672 |
| Miami, FL | $551,561 | +0.3% | −10.9% | −12% | −13.9% | −14.4% | −41% | $3,033 |
| Atlanta, GA | $383,651 | −0.4% | n/a | n/a | n/a | n/a | n/a | $2,110 |
| Boston, MA | $747,373 | +1.7% | +20.3% | −11% | −12.1% | −17.2% | −38% | $4,110 |
| Phoenix, AZ | $453,406 | −1.4% | +1.1% | +27% | −20.1% | −23.6% | −49% | $2,494 |
| San Francisco, CA | $1,811,133 | +16.8% | −7.0% | −26% | −14.3% | −15.7% | −23% | $9,961 |
| Riverside, CA | $567,002 | −2.2% | −4.1% | −16% | −20.4% | −23.2% | −42% | $3,118 |
| Detroit, MI | $209,264 | +3.1% | +0.3% | −9% | −10.8% | −12.7% | −23% | $1,151 |
| Seattle, WA | $797,197 | −5.1% | +22.3% | +18% | −28.7% | −35.7% | −54% | $4,384 |
| Minneapolis, MN | $398,599 | +2.2% | +7.2% | −7% | −17.7% | −21.7% | −38% | $2,192 |
| San Diego, CA | $921,759 | +3.7% | −2.2% | −22% | −26.6% | −30.5% | −51% | $5,069 |
| Tampa, FL | $373,686 | +1.0% | +5.4% | +22% | −11.2% | −14.1% | −45% | $2,055 |
| Denver, CO | $583,947 | +0.7% | +1.0% | +25% | −24.2% | −28.2% | −46% | $3,212 |
| Baltimore, MD | $408,564 | +0.9% | +8.4% | −22% | −16.3% | −20.3% | −39% | $2,247 |
| St. Louis, MO | $293,967 | +2.1% | +11.2% | −13% | −14.8% | −19.0% | −22% | $1,617 |
| Orlando, FL | $398,598 | −2.8% | +6.6% | +28% | −13.6% | −17.0% | −43% | $2,192 |
| Charlotte, NC | $398,599 | −3.4% | +2.9% | +11% | −17.4% | −20.8% | −39% | $2,192 |
| San Antonio, TX | $298,948 | −0.3% | −3.2% | +39% | −9.5% | −10.6% | −28% | $1,644 |
| Portland, OR | $551,960 | +1.3% | +1.7% | +4% | −21.3% | −25.1% | −45% | $3,036 |
| Sacramento, CA | $577,968 | −1.9% | +1.2% | −3% | −19.4% | −22.8% | −45% | $3,179 |
| Pittsburgh, PA | $261,082 | +6.5% | +5.5% | −17% | −5.0% | −6.8% | −16% | $1,436 |
| Austin, TX | $408,564 | −6.5% | −1.7% | +71% | −10.0% | −11.5% | −37% | $2,247 |
| Las Vegas, NV | $443,441 | +0.8% | −0.3% | −3% | −23.8% | −27.5% | −54% | $2,439 |
| Cincinnati, OH | $308,914 | +1.3% | +7.4% | −18% | −8.0% | −10.6% | −27% | $1,699 |
| Kansas City, MO | $347,777 | −0.6% | −1.7% | −14% | −8.9% | −10.2% | −22% | $1,913 |
| Columbus, OH | $353,756 | +1.2% | +4.9% | −1% | −12.8% | −15.8% | −29% | $1,946 |
| Indianapolis, IN | $308,914 | −0.4% | +8.9% | +15% | −11.8% | −15.3% | −25% | $1,699 |
| Cleveland, OH | $258,989 | +4.0% | +13.1% | −26% | −10.3% | −14.2% | −20% | $1,424 |
| San Jose, CA | $1,588,914 | −0.4% | +22.5% | −31% | −14.3% | −20.0% | −50% | $8,739 |
| Nashville, TN | $463,371 | −4.9% | +5.7% | +10% | −15.0% | −18.5% | −40% | $2,548 |
| Virginia Beach, VA | $370,697 | +1.6% | +3.5% | −23% | −12.7% | −15.5% | −24% | $2,039 |
| Providence, RI | $532,665 | +2.4% | +16.9% | −35% | −14.1% | −19.0% | −42% | $2,930 |
| Jacksonville, FL | $378,669 | +5.2% | −11.9% | 0% | −8.4% | −7.7% | −22% | $2,083 |
| Milwaukee, WI | $350,269 | −1.3% | +5.1% | −22% | −7.1% | −9.3% | −21% | $1,926 |
| Oklahoma City, OK | $269,054 | −0.3% | +2.4% | +31% | −18.5% | −22.0% | −28% | $1,480 |
| Raleigh, NC | $428,494 | −3.7% | +2.5% | −5% | −16.6% | −19.8% | −36% | $2,357 |
| Memphis, TN | $278,919 | −2.1% | +5.0% | +20% | −1.7% | −2.9% | −26% | $1,534 |
| Richmond, VA | $398,599 | −2.8% | +2.7% | −19% | −17.6% | −21.0% | −27% | $2,192 |
| Louisville, KY | $298,849 | +3.1% | +12.0% | +9% | −11.3% | −15.2% | −27% | $1,644 |
| New Orleans, LA | n/a | n/a | n/a | n/a | n/a | n/a | n/a | n/a |
| Salt Lake City, UT | $542,094 | −2.9% | +11.2% | +25% | −17.0% | −21.5% | −48% | $2,981 |
| Hartford, CT | $403,581 | +6.6% | +2.7% | −58% | −7.8% | −9.7% | −54% | $2,220 |
| Buffalo, NY | $293,917 | +5.0% | +25.8% | −1% | −9.2% | −14.7% | −20% | $1,616 |
| Birmingham, AL | $323,861 | +11.8% | −1.9% | −5% | −6.7% | −7.6% | −26% | $1,781 |
About the Data
Housing data. Redfin Data Center monthly data through October 2026, files updated November 3, 2026. All-home activity metrics use Redfin’s seasonal adjustment; median sale prices are unadjusted. Redfin now publishes the two in separate rows, with seasonally adjusted activity for the nation and its 100 largest metros; we pair them by region and month. The multifamily series uses observations explicitly marked as not seasonally adjusted. Redfin revises historical data as information arrives, so September figures here can differ from last month’s report.
Inventory and listings. Inventory measures listings active on the final day of the month. Active listings measures homes available at any point during the month. The report uses active listings for all supply measures and the buyer model; end-of-month inventory is used only in the inventory-flow residuals. These are distinct measures. Both measures exclude homes that have been on the market for more than one year.
Historical comparisons. Adjusted activity levels and monthly changes are compared across all prior months. Unadjusted levels and monthly changes are compared with the same calendar month or transition in earlier years. Annual percentage changes are compared across all prior months. Price, rate and payment level claims use same-calendar-month comparisons. Redfin’s current files begin in January 2016, so “highest” or “lowest in data going back to 2016” refers only to the period since then.
Estimated buyers. We infer a normalized buyer index from pending sales and active listings using a constant-returns Cobb-Douglas matching function. The listings elasticity is 0.16, following Genesove and Han (2012), and matching efficiency is normalized to one and held constant over time. Changes are conditional on that assumption.
Inventory-flow residuals. The dataset includes new listings minus pending sales minus the monthly change in inventory, and a version using closed sales. These are calculated residuals, not observed withdrawals. They can capture returns to market, coverage differences, revisions and seasonal-adjustment discrepancies; the closed-sales version also reflects closing lags.
Mortgage payments. The national rate is the average of October’s five weekly Freddie Mac readings, 7.328%, obtained from FRED. Payments use regional median sale prices and standard 30-year amortization at 10% or 20% down. The annual price-rate decomposition is an exact midpoint split. The same national rate is used for every region.
Coverage. The October panel includes 98 all-home metro regions with October data, of the 100 for which Redfin publishes seasonally adjusted figures, and 840 multifamily regions. Markets with fewer than 20 closed sales or 50 active listings, or missing values for either, are flagged as thin. National coverage and historical comparisons are separate from the selected 50-market table. The November report will follow Redfin’s next monthly release.
Sources
Redfin Data Center and methodology: https://www.redfin.com/news/data-center/ and https://www.redfin.com/news/data-center/methodology/
Freddie Mac, Primary Mortgage Market Survey, via FRED, MORTGAGE30US: https://fred.stlouisfed.org/series/MORTGAGE30US. Weekly data retrieved November 14, 2026.
Genesove, D., and Han, L. (2012). Search and matching in the housing market. Journal of Urban Economics, 72(1), 31–45. https://doi.org/10.1016/j.jue.2012.01.002