Markets Expect a Hike. The Fed Should Hold.

Key Takeaways
- August’s inflation acceleration was concentrated in energy, reflecting an oil-supply shock rather than an overheating U.S. economy. The relevant question is whether higher energy costs are spreading into underlying inflation.
- The literature does not say central banks should ignore supply shocks. It says the appropriate response depends on the source of the shock, its persistence and whether it feeds into wages, sticky prices and inflation expectations.
- That propagation has not happened in a meaningful way yet. Meanwhile, hiring remains weak, job gains are narrow, housing is under pressure and economic growth is unusually dependent on business investment. The Fed has room to hold and reassess.
The consensus around next week’s Federal Reserve meeting changed quickly. After Friday’s inflation report, 81% of respondents to MacroPolicy Perspectives’ flash survey expected a quarter-point rate increase, up from 56% before the report. Futures markets are pricing a similar outcome. What had looked close to a coin toss a few weeks ago now looks much more settled.
The change in expectations is understandable. Inflation has been above the Fed’s target for years, and another upside surprise raises the risk that progress has stalled. But the composition of the August report matters. Most of the acceleration came from energy, following another increase in oil prices tied to the Iran conflict and disrupted supply.
That makes the case for hiking less straightforward than the headline inflation number suggests. A rate increase can weaken demand when consumers and businesses are spending too aggressively. It cannot produce more oil. The relevant question for the Fed is whether this energy shock is beginning to spread into the parts of inflation monetary policy can influence.
So far, there is not much evidence that it has.
August’s inflation was an energy story
Consumer prices rose 0.4% in August and 3.4% from a year earlier, but energy accounted for much of the acceleration. Gasoline prices jumped 3.9% and contributed more than a third of the monthly increase. The same pressure was visible farther up the supply chain, where wholesale diesel prices surged 24.1%.
Higher energy costs can still create problems even when their source is outside the Fed’s control. Diesel raises transportation costs, and transportation is embedded in the price of almost everything households buy. Businesses facing higher fuel and freight bills will try to pass some of those costs along.
The question is how much they can pass through.
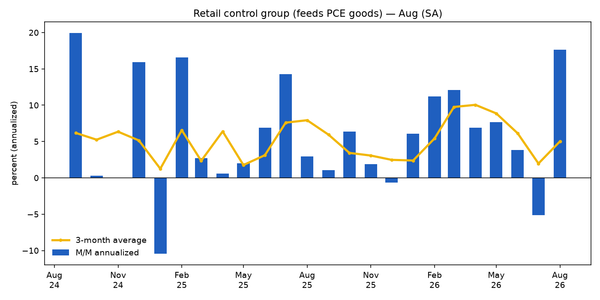
Excluding food and energy, core CPI inflation eased to 2.4% over the year. Monthly core inflation firmed somewhat, so the underlying inflation problem has not disappeared, but there is little sign in the August report that the energy shock has turned into a broad acceleration in consumer prices.
Household finances may also limit how much pricing power businesses have. Credit-card delinquencies are elevated, particularly at smaller banks, and younger borrowers have experienced some of the largest increases in serious delinquency. A growing number of households are also using installment products for basic purchases such as groceries.
When consumers have less room to absorb higher prices, businesses have fewer good options. Some of the increase in costs can be passed through, but some will show up in smaller margins, slower hiring or lower employment. Raising interest rates adds pressure through those same channels without addressing the source of the energy shock.
The economy remains resilient, but the growth is narrow
None of this means the economy is in recession. Private demand has held up better than headline GDP suggests, and consumer spending has remained resilient.
The composition of growth is nevertheless important.
Real GDP increased at a 1.5% annual rate last quarter. Business investment, led by spending associated with artificial intelligence and data centers, contributed roughly 1.2 percentage points of that growth. Everything else combined contributed only about 0.3 percentage point. At the same time, real final sales to private domestic purchasers increased roughly 4%, showing that underlying private demand remains stronger than the headline GDP number alone would imply.
Those figures are not contradictory. They describe an economy that is still expanding but increasingly dependent on a relatively small number of strong areas.
Housing sits on the other side of that divide. Existing-home sales remain near multi-decade lows, new-home demand has weakened and household formation has slowed. The typical first-time home buyer is now 40 years old, as high borrowing costs continue to delay entry into homeownership.
That weakness matters outside real estate. Housing turnover supports construction, furniture, appliances, brokerage, mortgage lending and a long list of local services. Those are also some of the areas most exposed to higher interest rates.
Another hike would therefore fall hardest on parts of the economy where monetary restraint is already clearly working.
The labor market tells a similar story
Employment growth improved in August, but here too the headline was stronger than the underlying breadth.
Employers added 162,000 jobs, while June and July were revised higher. But nearly two-thirds of August’s increase came from restaurants and local-government education. Over the past three months, payroll growth has averaged only about 71,000 jobs per month.
The longer view is even more concentrated. Health care and social assistance have accounted for most of the economy’s net job growth over the past year, while employment has declined in manufacturing, transportation and information. Federal employment has also fallen sharply.
What has prevented this slowdown in hiring from becoming a much weaker labor market is that layoffs remain relatively low. Employers are not hiring aggressively, but most are not firing aggressively either. The result is a labor market with little churn: workers who have jobs tend to keep them mostly because the number of alternatives is dwindling, while workers looking for work are taking longer to find it.
That distinction matters for monetary policy. There is little evidence that excessive hiring or rapid wage growth is driving the latest increase in inflation. At the same time, further monetary tightening would weaken demand in a labor market where hiring is already unusually soft.
The case for hiking deserves to be taken seriously
The argument for raising rates is not frivolous. Core PCE inflation has remained near 3.3%, progress toward the Fed’s 2% target has slowed, and policymakers have spent several years watching inflation prove more persistent than expected. That history raises the cost of assuming that another supply shock will simply pass.
The risk is that higher energy prices begin changing how households and businesses behave. Workers may demand larger wage increases, businesses may raise prices in anticipation of higher future costs, and a temporary oil shock can become a broader inflation problem.
There are some warning signs. The University of Michigan’s preliminary September survey showed year-ahead inflation expectations jumping to 4.6% from 4.0%, while long-run expectations edged up to 3.4% from 3.3%. But the New York Fed’s August survey was calmer: one-year expectations held at 3.6%, three-year expectations fell to 3.2%, and five-year expectations held at 3.0%.
Financial markets look calmer still. After the CPI report, five-year breakeven inflation was 2.40% and the 10-year breakeven was 2.36%, both lower than the day before. Those measures include risk and liquidity premiums, so they are not pure forecasts, but they do not suggest investors suddenly expect inflation to break loose.
Professional forecasters tell a similar story. In the September MacroPolicy Perspectives survey, five-year CPI expectations fell to 2.6% from 2.7% in June and five-year, five-year-forward expectations fell to 2.4% from 2.5%. Both remain above pre-pandemic levels, but neither is moving as though the inflation anchor has broken.
The timing matters. Those longer-run professional expectations were collected before the August CPI report, while the 81% expectation of a September hike came from the smaller post-CPI flash survey. Friday’s data clearly changed views about what the Fed will do. So far, consumer and market measures give much less evidence that it changed beliefs about where inflation is headed over the longer run.
What the literature says about an energy shock
The monetary-policy literature does not support a simple rule that central banks should ignore supply shocks. It supports a more useful conclusion: policymakers should distinguish a change in relative prices from an increase in underlying inflation and respond to the economic forces behind the price increase rather than mechanically responding to headline inflation.
Aoki (2001) provides the basic intuition. Some prices, including energy prices, can change quickly, while many other prices and wages adjust slowly. When the price of energy rises because supply falls, energy needs to become more expensive relative to other goods. Trying to prevent the overall price index from rising would require pushing other prices lower, which monetary policy can accomplish only by weakening demand.
That does not make an energy shock harmless. It means that stabilizing headline inflation immediately can impose unnecessary costs on the rest of the economy.
Bodenstein, Erceg and Guerrieri (2008) show the same tradeoff in a model that explicitly includes energy. When energy becomes more expensive, households lose purchasing power and the economy has to adjust. Policymakers can try to prevent much of the increase in prices, but doing so requires enough weakness in demand to put downward pressure on other prices and wages. More of the adjustment then occurs through weaker output and employment.
Alternatively, policymakers can tolerate some temporary increase in inflation while wage growth and other prices adjust more gradually, reducing the damage to employment.
Importantly, the paper does not conclude that interest rates should never rise after an energy shock. In the authors’ model, the appropriate interest rate does rise. Their result is that monetary policy performs better when it balances inflation stabilization against the cost to employment rather than trying aggressively to erase the inflation created by higher energy prices.
The paper also shows why headline inflation can occasionally send the wrong signal in the opposite direction. If an energy-price increase is expected to reverse quickly, forecast headline inflation can fall even while underlying inflation remains firm. A central bank responding mechanically to that forecast could leave interest rates too low.
The lesson is therefore not to ignore headline inflation. It is that headline inflation becomes a less reliable guide to the appropriate interest rate when energy prices are moving sharply. Policymakers need to know what is happening underneath it.
Clarida, Galí and Gertler (1999) reach the broader version of the same conclusion. Cost-push shocks create a tradeoff between stabilizing inflation and stabilizing economic activity. When policymakers care about both objectives, the optimal response generally brings inflation back toward target over time rather than trying to reverse the entire shock immediately.
The source of the oil-price increase matters as well. Bodenstein, Guerrieri and Kilian (2012) show that an oil-supply disruption, stronger global demand and stronger domestic demand can all raise oil prices while producing very different implications for monetary policy.
That distinction is especially relevant now. Oil prices are rising because supply has been disrupted. The increase is not evidence that U.S. households or businesses suddenly began spending too aggressively.
The experience of 2021 still matters
There is an important warning on the other side of the literature.
Gagliardone and Gertler find that the inflation surge that began in 2021 reflected both supply shocks and unusually easy monetary policy. That experience shows why a central bank cannot simply label inflation a supply problem and stop paying attention. If policy is too loose and a supply shock begins spreading into wages, expectations and broader prices, looking through the shock for too long can allow temporary inflation to become persistent.
The starting point today, however, is very different from the one the Fed faced in 2021.
The federal funds rate was near zero then. Today it is 3.50%–3.75%. The median participant in the September MacroPolicy Perspectives survey estimates the longer-run neutral policy rate at 3.375%. Neutral is uncertain and cannot be observed directly, but today’s policy stance is clearly far removed from the extraordinary monetary accommodation that accompanied the beginning of the previous inflation surge.
That changes the question facing the Fed. Policymakers are not deciding whether to leave rates near zero while inflation rises. They are deciding whether an additional quarter-point increase is needed on top of a policy rate that is already restraining housing, credit and other interest-sensitive activity.
The evidence for that additional restraint should therefore come from signs that the shock is spreading, not simply from the fact that energy prices rose.
History offers a reason for humility
The empirical record around oil shocks and monetary policy is less settled than the theory.
Bernanke, Gertler and Watson (1997) argued that monetary tightening following historical oil shocks amplified the resulting economic downturns. Later research challenged the size of that effect. Hamilton and Herrera showed that the results were sensitive to model specification, while Kilian and Lewis found little evidence that the Fed’s systematic response to oil prices explains the large swings in economic activity historically associated with oil shocks.
The literature therefore does not support the claim that monetary tightening caused most past oil-shock recessions.
It does support a more modest warning: when an economy is already absorbing the loss of purchasing power created by a negative supply shock, policymakers should be careful about adding more demand weakness unless that tightening is needed to prevent broader inflation from taking hold.
Recent work by Beaudry, Carter and Lahiri puts the decision in similar terms. In their framework, it can initially make sense for a central bank to look through a supply shock, but that changes if inflation begins feeding into expectations and becoming self-reinforcing. Once that threshold is crossed, delaying the response can become more costly than tightening.
No model tells us exactly where that threshold sits in September 2026. That has to be judged from incoming data.
For the Fed, the useful question next week is therefore not simply whether August inflation was high. It is whether the oil shock is beginning to show up in longer-run inflation expectations, wages and the sticky-price components of inflation.
If those measures begin accelerating, the case for another hike becomes much stronger.
They have not done so yet.
The case for holding
The Fed does not need to treat every increase in headline inflation as a test of its credibility. Credibility also depends on identifying the source of inflation correctly and using monetary policy where it can actually work.
August brought a meaningful increase in inflation, but most of the deterioration came from energy. At the same time, hiring remains weak and concentrated, housing is under pressure and economic growth continues to rely heavily on a relatively narrow investment boom.
Financial conditions have tightened as well. Markets already expect another rate increase, and long-term yields and mortgage rates have moved higher. Some of the restraint policymakers are seeking is already reaching the economy before the Fed makes another move.
None of that means the Fed can stop worrying about inflation. If higher energy prices begin pushing up wages, underlying inflation or longer-term expectations, policymakers should respond. The literature is clear that allowing a supply shock to become embedded can be costly.
The evidence that would justify tightening through this shock simply has not arrived yet.
Holding rates next week would give the Fed time to see whether August was the beginning of broader inflation or what the data currently suggest: an energy shock hitting an economy that is still growing, but with increasingly little room for error.
That is a good reason to wait.